The short answer is that cause decides coverage
Homeowners insurance in the United States generally covers water damage that is sudden and accidental, such as a supply line that bursts or a water heater that fails. It generally does not cover damage from gradual leaks, neglect or flooding, and the exact wording differs from one policy to another. If you live in Wheeling, WV, the first thing to do is read your own policy, because no blog can tell you what yours says.
Think of the question in three parts. What was the source of the water? How fast did it happen? And what does the policy say about that kind of event? Those three answers usually settle the first conversation with your insurer.
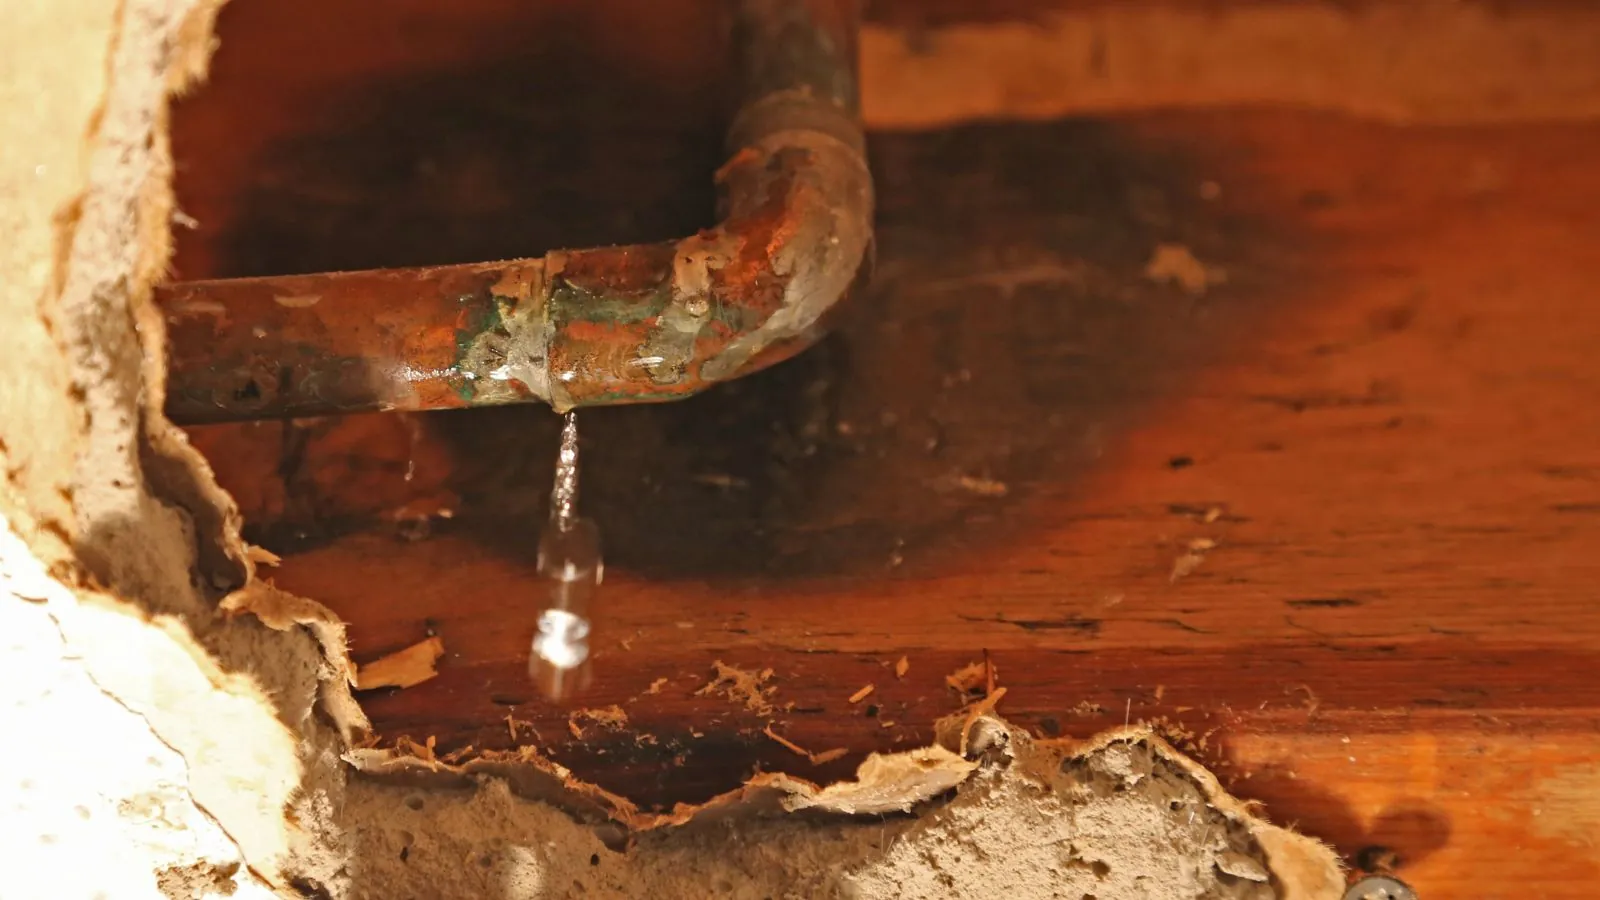
Sudden and accidental water
This is the category most people expect to be covered. A pipe that splits in a wall, an appliance supply line that comes off or a dishwasher hose that fails all count in most policies. Even then, the coverage often applies to the damage that follows, while the cost of repairing the failed pipe or appliance itself may not be covered. Ask your insurer which is which.
Speed matters. Insurers expect you to take reasonable steps to stop further damage, such as shutting the main water valve and calling for water removal. Keeping receipts for emergency work is a good habit.
Gradual leaks and neglect
A slow drip under a sink that runs for months, a roof leak that was ignored or a pipe that was known to be weeping may be treated as maintenance problems. Many policies exclude damage that develops over a long period. That is one reason to check under sinks and behind appliances regularly, and to fix small leaks promptly.
If you find old damage during cleanup, tell your insurer plainly. Being upfront about what you found and when is better than guessing.
Flooding is usually separate
Flood damage from rising river or surface water is usually excluded from a standard homeowners policy. It requires separate flood coverage, often through the National Flood Insurance Program or a private flood policy. The West Virginia Offices of the Insurance Commissioner directs people to the National Flood Insurance Program for flood insurance.
Wheeling sits on the Ohio River and has a documented flood history, so this is not a theoretical point. If your property is anywhere near the river or a creek, ask your agent what flood coverage you have and when it takes effect, since flood policies often have a waiting period.
A quick comparison
| Cause of water. | Often covered?. | Questions to ask your insurer. |
|---|---|---|
| Burst pipe or failed supply line. | Often yes, if sudden. | Does it cover the damage and the pipe repair?. |
| Water heater failure. | Often yes for the water damage. | Is the heater itself excluded?. |
| Slow leak over weeks or months. | Often no. | How does the policy define gradual?. |
| Sewer or drain backup. | Only with a specific endorsement. | Do I have sewer backup coverage?. |
| River or surface flooding. | Usually no. | Do I have a flood policy?. |
| Wind driven rain through the roof. | Often yes if the roof was damaged by a covered event. | Is roof wear excluded?. |
This table is general. Your policy language controls.
Questions worth asking before a loss
- What is my deductible for water damage, and is it different for wind or hail?.
- Do I have sewer or drain backup coverage?.
- Is there a limit on mold or water damage claims?.
- Does the policy require me to keep the home heated in winter?.
- Do I need to use a company from a preferred list, or can I choose?.
- What documents do you need after a loss?.
If you have already had a loss, call your insurer early and ask what they want to see. Ask for the claim number and the adjuster contact, and write down the date and time of the call.
How restoration and insurance fit together
A restoration company does not decide coverage. The insurer does. What a company can do is document the loss clearly, with photos, moisture readings and a written scope, so the insurer can review it. We do not promise that any claim will be approved or state what a claim will pay, and no honest company can. See the structural drying page for how readings are recorded, and the water extraction page for the first steps after a loss.
Local note for Wheeling, WV
Wheeling has a documented river flood record. According to the West Virginia Encyclopedia, the Ohio River crested at 55.2 feet in March 1936, more than 15 feet above flood stage. Local reporting based on Wheeling-Ohio County Emergency Management figures said the river reached about 41.85 feet in April 2024. If your home is on Wheeling Island, along the river or near a creek, flood coverage is worth a direct conversation with your agent.
For the residents of Benwood and Wellsburg, where the river is part of daily geography, the same applies. The state insurance office handles consumer questions about policies, so a call there is also an option if you cannot get a clear answer from your insurer.
Common questions
Does insurance cover water damage from a washing machine overflow?
Often yes if the overflow was sudden. Check for exclusions and ask your insurer.
Will my premium go up if I file a water damage claim?
It can. Ask your insurer how claims affect your policy before filing small ones.
Do I need flood insurance if I am not in a flood zone?
Flood damage can happen outside mapped zones. Ask your agent and check the FEMA flood map for your address.
If my Wheeling Island basement floods from the river, is that a homeowners claim?
Usually not. River flooding is generally excluded from a standard homeowners policy and falls under flood coverage. Ask your agent whether you have a flood policy.